Business Credit Score: How to Build a Good Credit Profile
8 July 2025

A good credit profile acts as the foundations for your finance strategy. But what can you do to build and nurture a good credit profile and business credit score?

When owning or first starting out in business, having access to finance will be fundamental to your success. And being able to borrow funds, or attract investment, will be dependent on you having a good business credit score and a healthy credit profile as a business.


Let’s explore how you can build up your credit profile.


Why is your credit profile important?


Funding is key for any business. Banks will lend to you and private equity investors will put money into the business – but only if they see the business as viable.


In short, lenders and investors want to be confident that you’re a low-risk prospect, with viable income streams, good cash flow and the capability to repay the loan, or deliver a return.


Your credit profile lists your credit history, payment history and your public financial records, to give an overview of the general creditworthiness and risk level of your business.


Key factors that affect your credit profile


Your credit profile evolves over time, along with the business. And your overall business credit score is not static. By being responsible with your use of credit facilities and your overall financial governance, you can improve your credit score and open up more routes to funding.


Here are some ways you can grow your credit profile as a business.


Pay your suppliers and debts on time:


Always pay your bills, invoices and loans before their due dates. This demonstrates that you’re reliable and financially responsible, factors that are heavily weighted by credit reporting agencies (CRAs) and lenders when assessing your business's creditworthiness.


Keep your credit utilisation ratio low:


Don’t use the full amount of credit that’s available to you. A high credit utilisation ratio can signal financial distress, so aim to use well under 30% of your available credit limit. Keeping this ratio low, shows you’re responsible and can have a positive effect on your credit score.


Don’t apply for multiple lines of credit:


Applying for multiple lines of credit or loans in a short period can be a major red flag to lenders and CRAs. Each application can result in a hard inquiry on your credit report, which can temporarily lower your score. Only apply for credit when it’s genuinely needed.


Get a business credit card and use it responsibly:


Using a business credit card for regular, manageable expenses, then paying off the balance in full each month, builds a positive credit history. This credit history is separate from your personal credit score and demonstrates that the company can manage its finances and credit well.


Keep your debt-to-equity balance healthy:


Make sure the business isn't overly reliant on debt compared to its own equity. A balanced capital structure is a good sign of financial stability to lenders, showing that you have a strong financial foundation to support your obligations and future growth.


Keep your financial records and filings up to date: Make sure you’re updating your financial records, statutory accounts and company filings. This makes it easier for the CRAs, lenders, and investors to access your public records, check for good governance and form an opinion on your creditworthiness.


A good credit profile acts as the foundations for your finance strategy, putting you on solid ground to reinvest in the business and begin the next stage in your start-up growth.


Come and talk to us about other ways to improve your business credit score, sure up your finances, and get the funding you need to bring your strategy to life.

man reviewing documents
5 October 2026
When was the last time you reviewed your business spending? We suggest a few key ways to review, manage and mitigate your operational costs and overheads.
calculator with the word cashflow on it
28 September 2026
Positive cashflow is the beating heart of your business. Dive into a Plain English guide to cashflow and find out how to get in control of your cash position.
hand putting money in piggy bank
15 September 2026
As a business owner, how much should you pay yourself? It depends on how much your business can afford, market pay rates, and whether reinvestment could pay dividends.
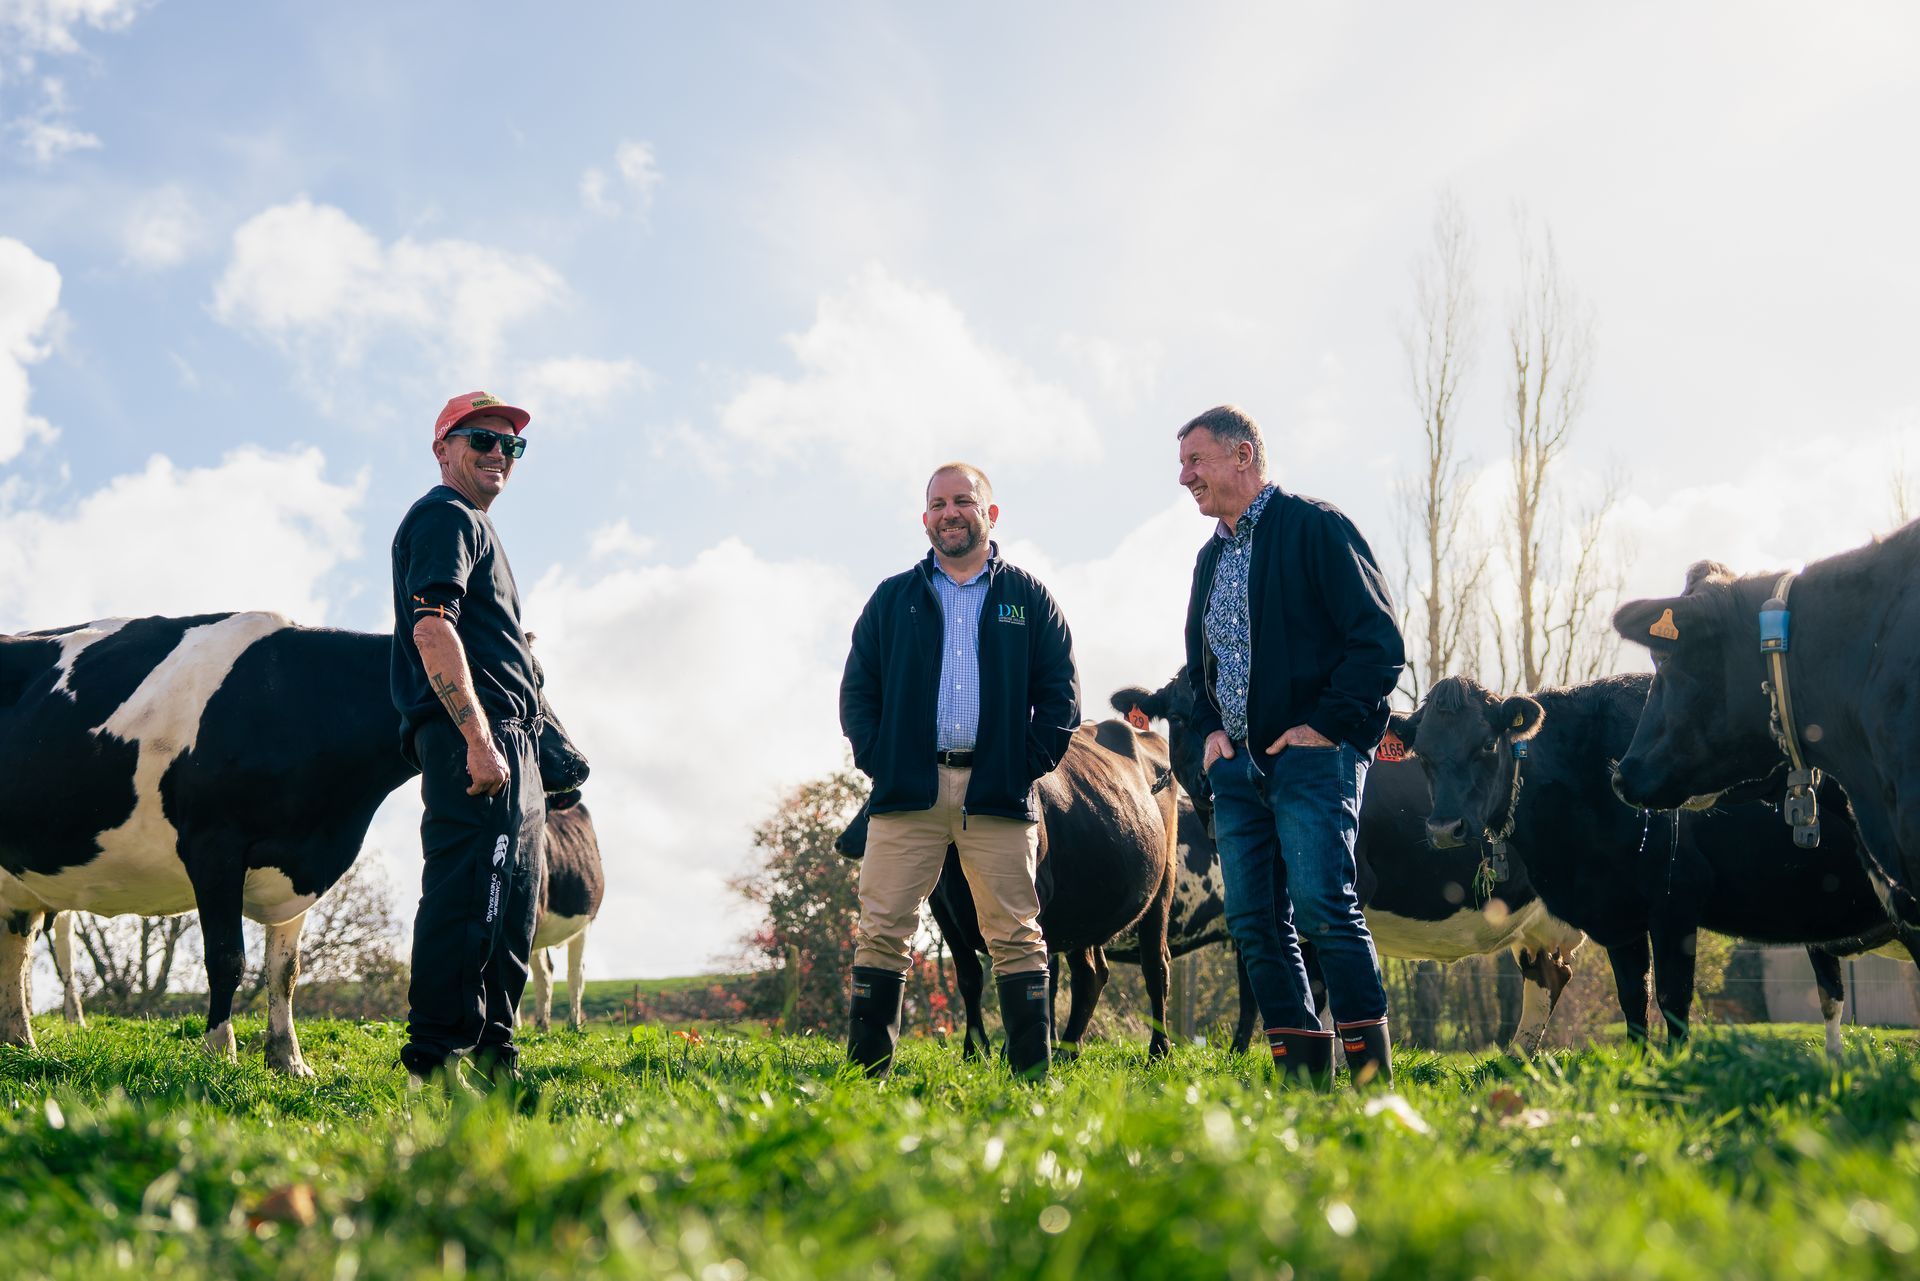
Better information supports better farming decisions
14 July 2026
We recently caught up with our clients Graeme and Margaret Shaw to talk about their farming journey, the goals they have worked towards and what has helped them make progress along the way.
Better tax planning, better business decisions
8 July 2026
Tax planning is about looking ahead, understanding your obligations and making informed decisions before the end of the financial year.
Making the most of your accountant’s advice
1 July 2026
Most business owners know their accountant plays an important role in keeping the numbers on track. From accounts and tax obligations through to regular reporting, good accounting support gives you a clearer view of how your business is performing.
Creating your initial Succession Plan
26 May 2026
It's never too soon to create a Succession Plan for your business! The longer you have to plan your exit strategy, the more value you can extract. Don't leave money on the table or be forced to work longer, start planning now!
How an accountant supports your business: 5 key areas of focus
14 May 2026
A good accountant talks to you regularly throughout the year. Here are five key ways we can support your financial management and the performance of your business.
Are you up to speed with the recent changes to fringe benefit tax (FBT)?
4 May 2026
Do you provide fringe benefits to your employees? If so, you may need to update the tax treatment of these benefits to fall in line with the new fringe benefit tax (FBT) legislation.
New: Contract Milking Accelerator Programme
6 April 2026
We’ve recently launched a new Contract Milking Accelerator Programme, designed to support contract milkers in managing the financial side of their business.
Show More